
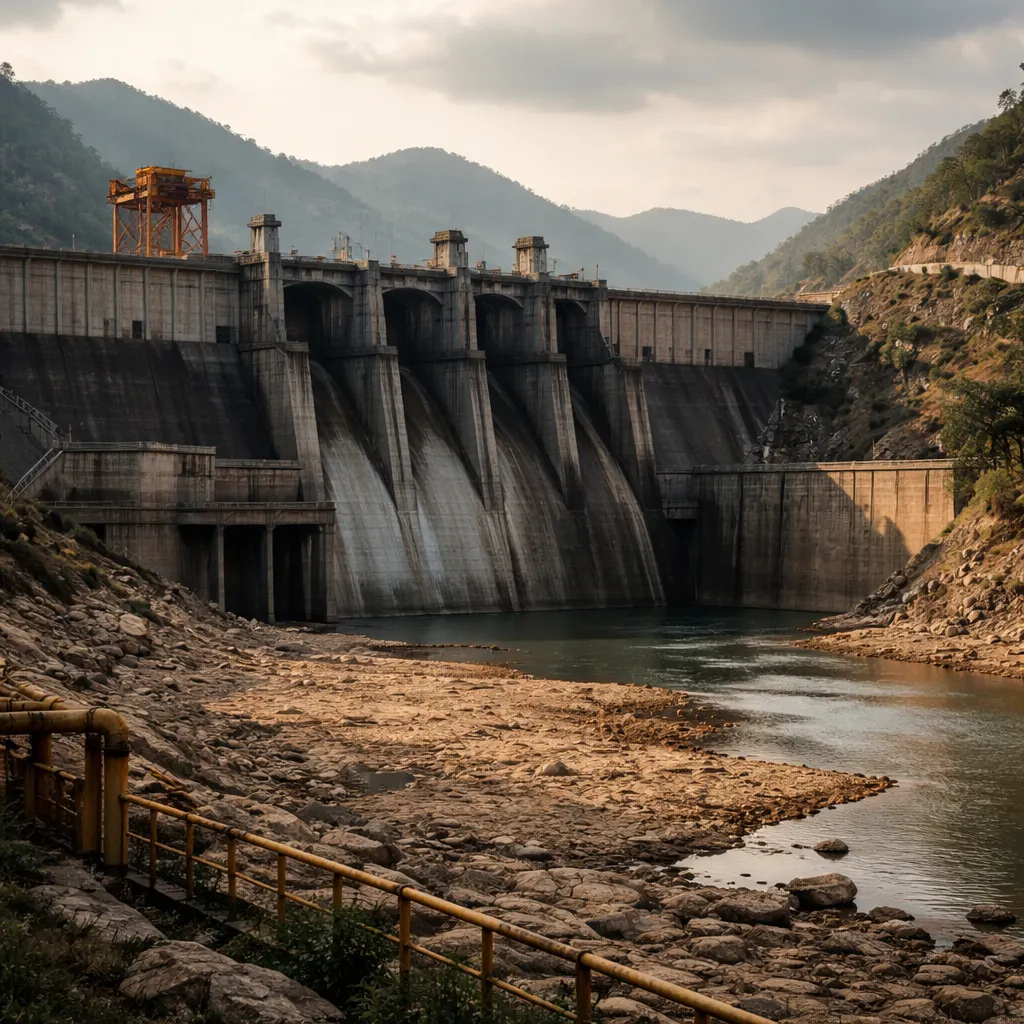
Hydropower and Electricity Corporation No. 3 recorded a 25% drop in after-tax profit during the third quarter of 2026, falling to nearly 5.9 billion VND from almost 7.8 billion VND in the same period last year, according to the company's financial report for Q3 2026 published this month. The Vietnamese power generator blamed insufficient water supplies for electricity generation, which led commercial electricity output to decline 16% compared to the year-ago quarter. The company trades on the Ho Chi Minh Stock Exchange under the ticker DRL and operates the Dray H'Linh 2 hydropower facility in Dak Lak province.
Net revenue reached 17.2 billion VND in Q3 2026, down 18.4% from 21.1 billion VND in the same quarter of 2025. The cost of goods sold came to nearly 9.1 billion VND, falling roughly 9% year-over-year, but the steeper revenue decline resulted in gross profit dropping 26.7% to 8.13 billion VND. Financial income climbed about 49% to 1.34 billion VND from nearly 900 million VND the previous year, while business management costs edged down from 2.1 billion VND to 2.02 billion VND. For the first nine months of 2026, the hydropower company posted net revenue of 60 billion VND, down 13.6% from 70 billion VND in the corresponding 2025 period, with after-tax profit totaling almost 27.7 billion VND compared to 33.9 billion VND a year earlier, representing an approximately 18.2% decline.
According to the company's explanation, the primary driver behind these results was water inflow for electricity production coming in below expectations, which triggered the 16% decrease in commercial electricity generation and the resulting 18% fall in commercial electricity sales revenue versus the prior-year quarter. On the cost side, the report notes that several government-mandated reductions—including charges for forest management and water resource taxes—produced an 8% decrease in total costs during Q3 2026 compared to the same period last year, though these savings proved inadequate to compensate for the revenue shortfall.
The water scarcity that crimped production highlights the vulnerability of hydropower operations to climate and hydrological conditions. While government policy changes lowered operating expenses by cutting forest management levies and water resource taxes by 8%, the revenue hit from reduced electricity output overshadowed the cost relief—revenue fell more than twice as fast as costs declined. The company's balance sheet remained relatively healthy, with total assets rising 6.6% to 135.6 billion VND by September 30, 2026, while total liabilities dropped about 16.7% to 14.6 billion VND. Cash and cash equivalents surged from 595 million VND at year-start to 13.9 billion VND, and short-term investments grew from 56.6 billion VND to 67.8 billion VND, even as short-term receivables fell from 25 billion VND to 9 billion VND.
The company recently announced it will distribute an interim cash dividend for the first quarter of 2026 at 15%, equivalent to 1,500 VND per share, with the record date set for October 15 and payment expected on October 28. With 9.5 million outstanding shares, the firm anticipates disbursing approximately 14.25 billion VND for this dividend. Central Power Corporation, which holds nearly 2.9 million shares representing 30.42% of the company's capital, stands to receive about 4.3 billion VND from this payout. Hydropower and Electricity Company No. 3 specializes in electricity generation and trading, managing and operating the Dray H'Linh 2 hydropower plant in Dak Lak, which produces commercial electricity for direct and exclusive supply to the Central Power Company across the Dak Nong and Dak Lak provinces.