
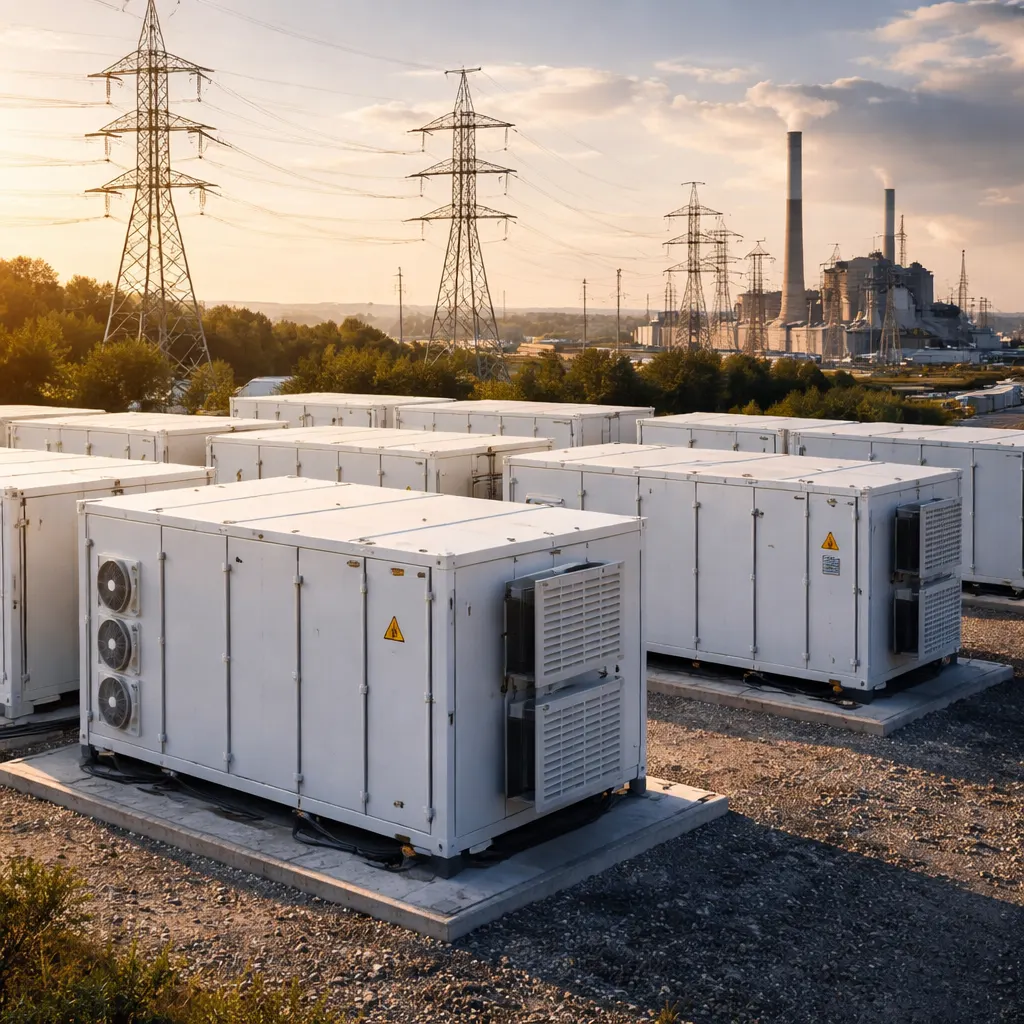
The cost of electricity from four-hour battery storage has dropped below the price of gas peaker plants in markets worldwide, according to a Wood Mackenzie analysis published Thursday. The firm's report signals a decisive economic shift favoring renewable energy and storage over traditional fossil fuel infrastructure. In North America, the transition is being accelerated by data center demand and shortages in gas turbine manufacturing capacity.
In the United States, four-hour battery storage for projects coming online in 2026 costs 65% to 75% less than new open-cycle gas turbine peakers, depending on whether carbon pricing is applied at the state level, a Wood Mackenzie spokesperson told Utility Dive. Gas turbine prices are projected to climb to $600 per kilowatt by the end of 2027, representing a 195% jump since 2019. The three major manufacturers — GE Vernova, Siemens Energy, and Mitsubishi — currently hold backlogs ranging from 35 gigawatts to 116 gigawatts as they plan capacity expansions. In the Middle East and Africa, four-hour storage costs are forecast to decline 33% to $80 per megawatt-hour by 2035, displacing gas peaking across every gas market in the region. China maintains the global storage cost benchmark at more than 55% below the rest of the Asia Pacific average.
"This economic shift is decisive and widening," Ahmed Jameel Abdullah, principal analyst at Wood Mackenzie, said in a statement. "Gas turbine shortages and rising fuel volatility are driving up peaking costs, while expanding battery manufacturing continues to push storage costs down." The report finds that single-axis tracker solar is now the lowest-cost new-build technology in 43 of 48 modeled markets, with onshore wind leading in five. In the most competitive markets — Saudi Arabia and the United Arab Emirates — solar costs are projected to fall below $20 per megawatt-hour by 2033.
The cost reversal stems from supply constraints colliding with surging demand, the analysis explains. North America faces a supply deficit cycle for gas generation capacity extending through the late 2030s, driven by data center load growth that keeps thermal capital costs elevated and strengthens the long-term economic case for renewables and storage. Meanwhile, battery manufacturing scale continues to expand, with China's production volume illustrating how manufacturing scale is redrawing the global cost map. For onshore wind, continuous improvements in capital and operating expenses are expected to drive costs down 16% by 2060, despite near-term uncertainty from policy changes and potential tariff impacts on turbine pricing. Tax credits for energy storage continue to provide a competitive advantage by partially counteracting foreign entity of concern restrictions and supply chain constraints.
Near-term headwinds remain for certain technologies, particularly solar in North America, where tariffs, anti-dumping and countervailing duty actions, and new import restrictions are pressuring costs. Distributed solar faces the most significant price increases, while utility-scale solar is partially protected by 168 gigawatts of safe-harbored capacity, though module prices are still expected to rise around 5% annually through 2030. Residential and commercial projects confront a more constrained environment, with module prices forecast to increase 6% in 2027 and another 14% in 2028. For energy storage, a cost spike is anticipated following the phase-out of investment tax credits from 2038, but over the long term new battery chemistries, hardware commoditization, and domestic supply chain expansion are expected to drive storage costs down 10% by 2060.